
Equipment Loan
Machinery on the shortlist? An excavator, a generator, farm machinery or the workshop's next band saw: every class of equipment meets a different lender appetite, and the job here is knowing which lender fits the machine before the application goes anywhere.
- Pre-approval typically inside a day
- A no-cost rate indication

What to expect
Name the machine
Apply online with the equipment you are pricing and the amount to finance, whether it is fresh off a dealer's floor, imported to order or standing used in someone else's yard.
A soft first check
The first credit check is a soft one that costs your score nothing, and review begins the same day the application arrives.
Matched on lender appetite
Criteria from over 40 lenders are read against the machine itself, because appetite moves with equipment class: some lenders carry no deposit requirement while others want 20% or more.
Sign, and take delivery
Approval fixes the costs and conditions in writing, the documents are signed electronically, and the vendor is paid directly, leaving delivery as the only thing left to schedule.
With clean credit the deposit can be $0, and paying one anyway will not buy a lower rate.
Run the machine's numbers
Your repayment
*Estimates only, never offers; lending criteria and the site's terms and conditions apply.

Band saws to excavators
Equipment finance covers a strange catalogue. Modern medical equipment, cameras, band saws, generators and the excavator out on the earthworks all sit under the one label, whether the buyer is a business scaling up, an operation due for an upgrade or a hobby home business replacing its gear.
Underneath that label the market runs on niche policy. Different equipment carries different requirements with different lenders: some hold appetite for no deposit where others want 20% or more, and some refuse generators outright yet will fund the same generator attached to a trailer. Knowing those policies before anything is lodged is where a broker saves you the most time.
The homework can run ahead of the application, too. Contacts at the lenders make it possible to test a concern in advance, whether it hangs over the machine, affordability or credit, and purchases beyond $250k can reach main-bank solutions with more flexibility than a standard five year term.
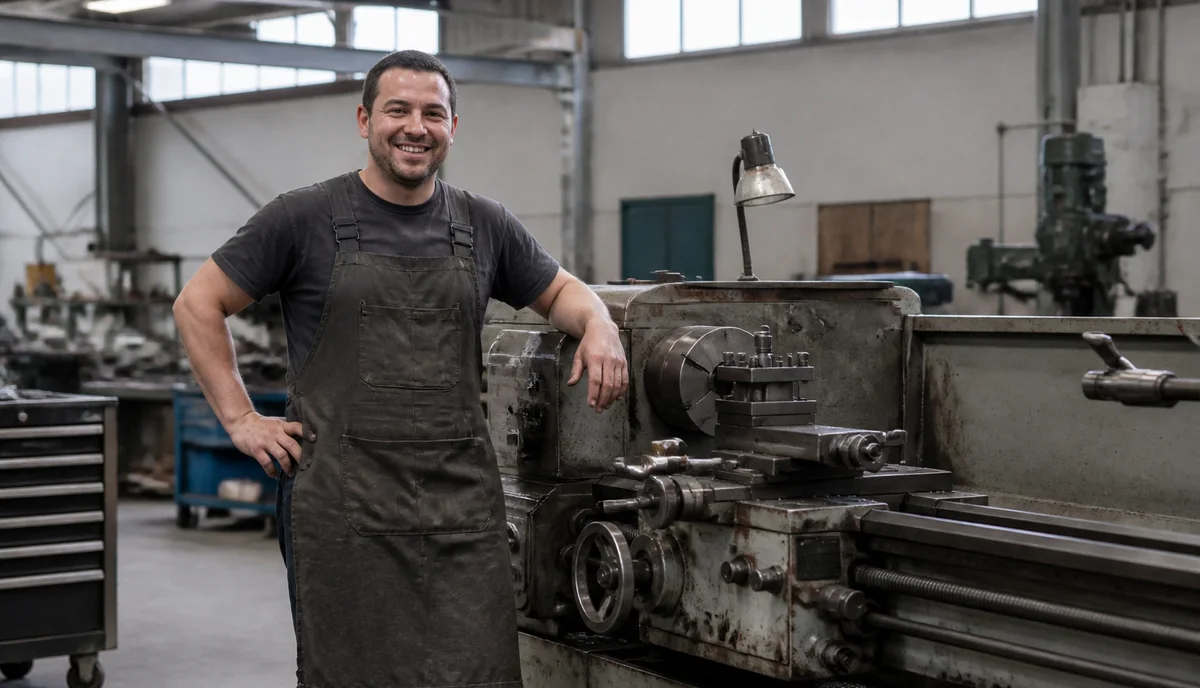 Workshop machinery
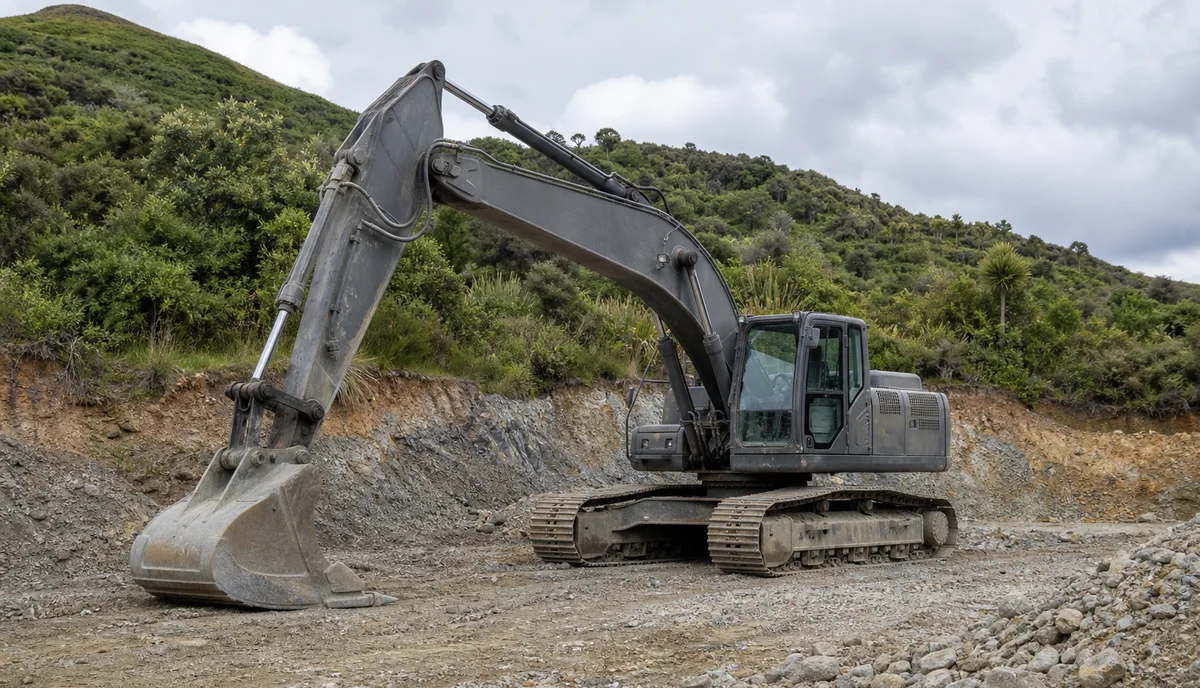 Earthmoving equipment
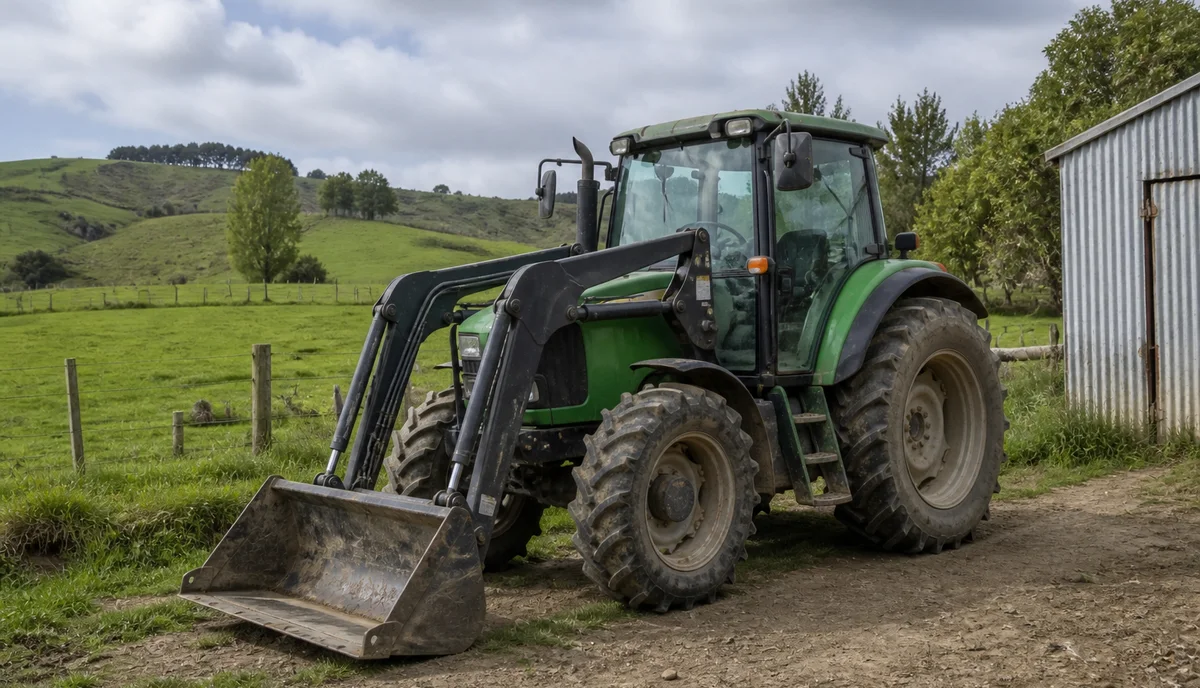 Farm machinery
Where an approval starts
The short checks
- You are over 18; from 18 to 21, a parental guarantor is the likely ask.
- Income from the business, full-time work or self-employment covers the repayments comfortably.
- The equipment can be insured, cover over the asset being a standard approval condition.
- Your identity stands up to the AML check that accompanies every approval.
Credit with a dent in it still gets a hearing. No set criteria sheet applies on the broking side, so one call names the lenders with appetite for your machine and your position, plus the rate range to plan around. Already declined somewhere? Say where, because it speeds the answer up.
Quicker to say it than type it? Dial 0508 662 456 and describe the machine to Sam.
Equipment loan questions
Why would two machines carry different deposits?
Because appetite is set by equipment class, not by the borrower alone. One lender funds a class with nothing down while another wants 20% or more for the very same machine, so the application is steered to the lender whose policy suits the deal.
Can a generator be financed?
Usually, with a wrinkle worth knowing: some lenders decline generators outright yet accept a generator attached to a trailer. It is exactly the kind of niche policy that makes a phone call before ordering worthwhile.
Does secondhand equipment go through the same way?
It does, through the same process. An older asset is one of the situations where a deposit can be requested, alongside dented credit, so flag the machine's age when asking for an indication.
What about purchases beyond $250k?
Larger purchases can move past standard asset finance into main-bank solutions that offer more flexibility than a five year term loan allows, which matters when gear gets upgraded on a cycle.
Could the finance on our current gear be reviewed?
If the interest on it feels too high, bring it over. The loan is read against what the market offers now, and where savings exist you will hear exactly where they sit.
Will checking a rate touch my credit score?
No. A soft check opens every file precisely so your score takes no damage, and a full credit check waits until we have spoken with you.
How fast can equipment funding land?
Review happens the day the application arrives, anything in before midday can hold approval within the hour, and concerns about the machine can be tested with lender contacts ahead of time instead of mid-application.
What does the pre-approval actually lock in?
The interest rate, the repayment figure and any lending conditions, in writing. Signed documents, the AML identity check and insurance over the equipment are the standard conditions, and none of it obliges you to draw down.
Test the appetite for your machine
One conversation and one soft credit check establish which lenders want the deal, and a pre-approval leaves the decision entirely with you.
Equipment finance is subject to lending criteria and the standard terms and conditions.