
Mortgages
A first home, the next one, an investment property, a refinance or a top-up? Mortgage advice here comes from qualified financial advisers who have done the formal study, and ridden the market's ups and downs with their own properties.
- A licensed financial advice provider
- Fee-free on main-bank lending

What to expect
Start with a conversation
Consultations are complimentary and open with your goals and budget, so the advice aims at where you want to end up rather than just the loan in front of you.
Build the file together
You get help gathering and organising the necessary supporting information for the application, the heaviest lifting in any mortgage, before anything goes near a lender.
Structured, then submitted
Together we work out a loan structure that suits your needs, and once the details are agreed, the application is submitted to the most suitable lender for it.
Questions, approval, keys
Depending on complexity the lender may come back with questions; once they are answered, approval arrives with its conditions, and with those met the documents and payout for your new property are arranged.
Hundreds of loans secured for our clients every year.
Recent case studies
Buying a $450k business with property equity
A married couple with two children had an opportunity to buy a business worth $450k, but needed to utilise equity in their property. We helped them top up their mortgage to within the LVR restrictions, whilst securing a general security agreement business loan, backed by the property up to 100% of the property value, to secure the last $100k. This is from the same bank they had tried approaching directly, who had said they couldn't assist.
The workshop lease that became a mortgage
A self-employed client was looking for a new premises to run his auto workshop from. He was growing exponentially, needed more space, and his lease was nearly up. He worked out that the lease cost of a new space was substantially more than a mortgage would be, but he had no deposit. Through a major bank's commercial policy we raised 65% of the loan as a mortgage over 15 years and the remaining 35% as an unsecured business loan over 5 years. The repayments initially are higher, but this resulted in minimal interest paid and securing a building to own, rather than lease.
Let us help you be the next success story.
Advice with skin in the game
The minimum requirement for this work is a level 5 certificate. Director Sam holds his Bachelor of Business Studies majoring in property on top of it, and has been a property investor since buying his first investment property at 21 while serving in the Royal New Zealand Navy; by 2021 the portfolio had grown to five.
Laura, who joined in 2024, holds a level 5 certificate in financial services and began her own property journey at 21 with a first home purchase. Having bought and sold multiple properties herself, she knows how stressful the process gets, for first-time buyers especially, and supports her clients through every step of it.
A broker who claims to know everything is a dangerous broker; the market is too big, and changes too often, for anybody to. The strength here is different: on the rare occasion something is not known, knowing exactly how to find the answer, then working from your goals, aspirations and current position to map what is available now and what to do together to reach them.
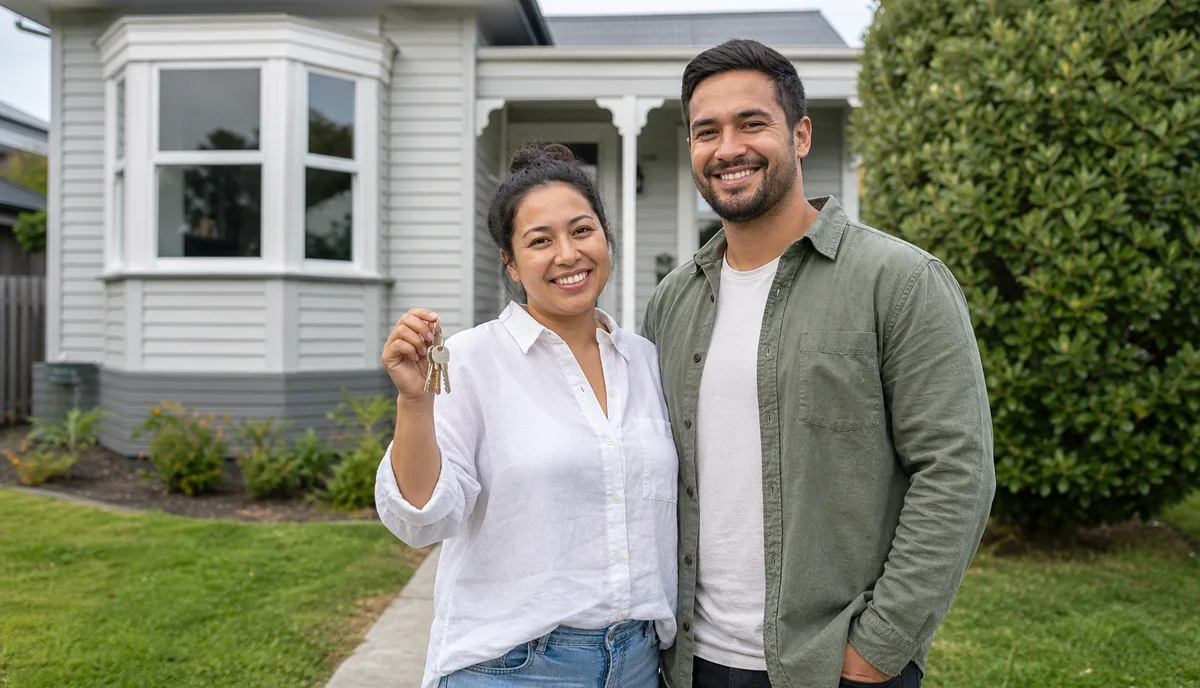 First homes
 Owner-occupied homes
 Investment properties
What the advice covers
What we advise on
- Your first or next owner-occupied home. A big step for anybody: the mortgage sourced and each stage project managed, so you know when to find a lawyer, a building inspector, or to seek KiwiSaver advice.
- A new investment property. A fantastic option for securing an enjoyable retirement; regulation changes constantly in this space, and as property investors ourselves we stay up to date with the changes and funding restrictions.
- Refinancing existing lending. Dissatisfied with your current lender? Your situation is evaluated and tailored refinancing options presented, with the steps and potential benefits explained, instead of you ringing bank after bank.
- Topping up an existing home loan. Under the Responsible Lending Code a top-up now mirrors a new application, which makes it the right moment to check your current bank is still the best fit.
The company built its reputation in asset finance for being fast and efficient, and the same skillset runs the mortgage side. Volume gives more negotiating power on rates than an individual has alone, and if a bank's offer sits out of line with the market, you are backed going back to them with what is available elsewhere. Where traditional lending will not fit, there are avenues standard mortgage brokers do not have.
Prefer to open with a person? The team is on 0508 662 456.
Mortgage questions
What does a mortgage broker cost?
Nothing, on main-bank lending. Being a mortgage broker, we do not charge clients fees because we are paid by the main banks: you can apply and go right up until the loan is drawn down without fees or charges, and in most cases main banks waive their application fees and provide a cash back on new lending that covers legal fees. Where a transaction is of a second-tier or high-risk nature and the provider does not pay us, a broker fee is included within the loan and disclosed up front.
Are you licensed to give mortgage advice?
Yes. Nobilo Finance Limited operates as a Financial Advice Provider under a current licence issued by the Financial Markets Authority (FSP 587268), permitted to provide direct advice relating to mortgages. The full picture of how we work and how we are paid sits in the mortgage advice disclosure.
Why use a broker rather than going straight to the bank?
Leverage and current knowledge. Volumes bring more negotiating power on rates than you have as an individual, and if the bank's offering is not fair and in line with the market, we back you when going back to the lender with what is available elsewhere. Working with most lenders keeps that comparison up to date.
How long does a mortgage take to arrange?
Longer than the asset finance this site is known for. Mortgages and commercial lending need the additional information and assessment banks require, so budget for building the file properly and for the lender's questions rather than for an hour-scale turnaround.
Will asking about a mortgage show on my credit file?
No. The first check is always a soft one, run so your credit takes no damage, and no credit check runs at all until we have spoken with you.
I am self-employed. Is that a problem?
It is familiar ground. Advising self-employed clients comes with knowing first-hand what it is to run a business, and where traditional lending will not work there is access to unique avenues that standard mortgage brokers do not have.
Which lenders do you work with?
Most of the market. Working with most lenders is what keeps the advice current on what is available, and it is the difference between comparing one bank's balance sheet and comparing the market.
Start with the conversation
A complimentary consultation and a soft credit check are how every mortgage here begins, and neither commits you to anything.
Mortgage advice is provided by Nobilo Finance Limited (FSP 587268), a licensed financial advice provider. Read the mortgage advice disclosure for how we work and how we are paid.